6 months 3 weeks ago
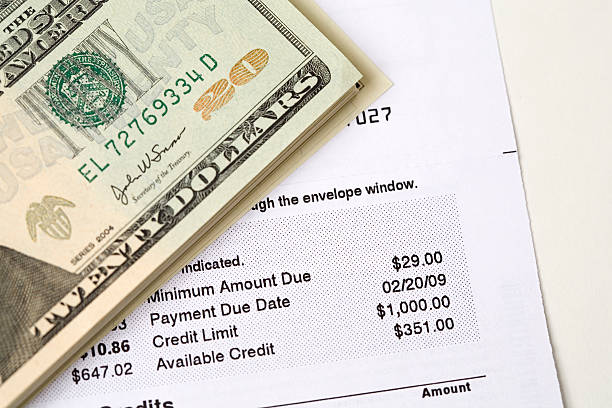
When you get your first credit card, the limit on it feels like a blessing. Maybe it’s $500, maybe it’s $5,000. Either way, that number looks like spending power. But if you treat your entire credit limit as money you’re allowed to use, you’re setting yourself up for a lower credit score and higher stress. The truth is, your credit limit is not a savings account or a pay raise. It’s a ceiling that comes with rules, and the smartest move you can make is to keep yourself far away from that ceiling.Here’s the simple math that most people never explain clearly. Your credit utilization ratio is the amount of credit you’re using compared to the amount of credit you have available. If your credit card has a $1,000 limit and you carry a $300 balance, your utilization is 30%. If you carry $900, it’s 90%. Credit scoring models like FICO look at this number and they love low utilization. In fact, utilization makes up a big chunk of your score, second only to payment history. Most people know you should pay your bills on time, but way fewer know that how much of your limit you’re using matters almost as much.The classic advice says keep your utilization under 30%. That’s true, but it’s also misleading. The “under 30%“ rule is a ceiling, not a goal. Someone using 2% of their limit looks much better to a credit score than someone using 29%. Think of it like a speed limit. You can drive at 65 miles per hour on a highway with a 65 mph sign, but you’ll feel a lot safer and get better gas mileage at 55. Same thing with your credit utilization. The absolute best scores often come from people who use less than 10% of their available credit. Some even use 1% or 2% and then pay it off completely.So what does that mean for your daily life? It means your credit limit should act like a budget boundary, not a spending goal. If you have a $5,000 limit, that doesn’t mean you have $5,000 to spend. It means the credit card company trusts you borrow up to that amount, but they’re watching how close you get to the edge. The closer you get, the riskier you look. Why? Because high utilization suggests you might be living beyond your means. It looks like you need credit to survive, not just to build history. That’s a red flag for lenders.The good news is that utilization is one of the easiest parts of your credit score to control. You don’t need to wait years for it to improve. You don’t need to dispute anything. You just need to change how you use your cards. The simplest strategy is to pay off your balance in full every month. Do that and your utilization will drop to zero on the day your statement is calculated. But here’s a tricky detail: your credit card company usually reports your balance to the credit bureaus once a month, and that report is often based on your statement balance, not what you pay by the due date. So if you spend $800 on a $1,000 limit card but pay it off before your due date, the credit bureau might still see an $800 balance if that’s what your statement showed. That makes you look 80% utilized, even though you never paid a penny in interest.The fix is simple. Pay your balance before the statement closing date, not just before the due date. Or make two payments a month. Or just keep your spending on each card so low that even the statement balance stays under 10% of your limit. If you’re using a card for groceries and gas, that’s easy. If you’re putting rent or a big purchase on it, you need to plan ahead. Another trick is to ask for a higher credit limit. If your income is steady and you don’t have too much debt, many card issuers let you bump up your limit with a quick request online. That instantly lowers your utilization because the denominator gets bigger. Just be careful not to use the new limit as an excuse to spend more.More cards can also help, but only if you actually manage them well. Having three cards with $2,000 limits each gives you $6,000 total available credit. If you only carry a small balance on one card, your overall utilization stays low. The catch is that opening too many cards at once can ding your score due to hard inquiries. So space it out and keep the old cards open even if you don’t use them. Closing a card shrinks your total available credit and can push your utilization up overnight.Here’s what this means for your long-term future. When you keep your utilization low, you’re not just getting a momentary score boost. You’re building a pattern that lenders can see. They look at your history over months and years. Someone who consistently uses 90% of their credit limit is seen as high risk, even if they always pay on time. Someone who uses 5% today and 15% next month looks stable. That matters when you apply for a car loan, a mortgage, or even an apartment rental. Your credit score isn’t just about getting a pat on the back. It’s about saving money. Lower utilization can mean lower interest rates on loans, which means thousands of dollars saved over a decade.Start treating your credit limit like a speed limit. You don’t have to hit it to prove you can. The safest lane is the one far from the edge. Spend a little, pay it off, and watch your score climb. That’s not boring. That’s the kind of boring that buys a house someday.Yes! The very best amount is your full statement balance to avoid all interest. If you can’t do that, aim to pay double the minimum, or even just a fixed extra amount like $25 or $50. Every single dollar you pay over the minimum helps you escape debt faster and saves you money. Something is always better than nothing.
Credit Karma is a top choice. It’s completely free and shows your VantageScore from two major credit bureaus. The app updates weekly, is very easy to use, and explains the factors changing your score. They make money by suggesting credit cards or loans you might qualify for, but you never have to buy anything to see your score and reports.
Don’t panic! You have the right to fix mistakes. First, contact the credit bureau that made the report with the error. You can usually dispute the mistake right on their website. Also, contact the company that provided the wrong information, like your bank. Explain the problem clearly and send copies of any papers that prove you are right. They must investigate and correct errors, usually within 30 days.
Your credit limit is the maximum amount of money your credit card company says you can borrow at one time. Think of it like a financial guardrail. It’s not a goal to hit or a suggestion for how much to spend each month. Knowing this number is your first step to using your card wisely and avoiding the stress of maxing it out, which can hurt your credit score.
Your credit score is like a report card for your money habits that lenders check. A good score means you can borrow money easier and cheaper. It helps you get approved for apartments, car loans, and even some jobs. Think of it as building a good money reputation now so future-you can get better deals and have more choices when you want to make big life moves.