If you want to build credit but aren’t ready for a credit card, a savings pledge loan offers a simple alternative. Also called a credit-builder...
today
Read More
When you get a raise, a new job, or a tax refund, it feels like permission to upgrade your life. You might want a nicer apartment, a newer car, or a...
today
Read More
Closing an old credit card feels like a clean move. You may be tired of managing another login, worried about fraud, or tempted by a simpler wallet....
today
Read More
Closing a credit card can feel like a clean way to simplify your wallet, but it can also backfire on your credit score. Before you cut up a card or...
1 day ago
Read More
If you are in your twenties and have never borrowed money, your credit file may look like a blank page. That can feel unfair when you want an...
1 day ago
Read More
Buy now pay later services have become a normal part of checkout for clothes, electronics, concert tickets, and even groceries. They let you split a...
1 day ago
Read MoreFocus on the one card you have or the one new card you get. Use it for small purchases and pay the full balance on time every single month. This builds a fantastic payment history, which is the biggest factor for a good credit score. Let your good habits with one or two cards build your score slowly and steadily.
Most services can report a wide range of your regular bills. Common ones include your rent payment, electricity, gas, water, internet, cable, and even some streaming subscriptions like Netflix. The key is that these are bills you pay consistently each month. The service will connect to your bank account or billing accounts to verify your payments. They then translate that payment history into a format the credit bureaus accept.
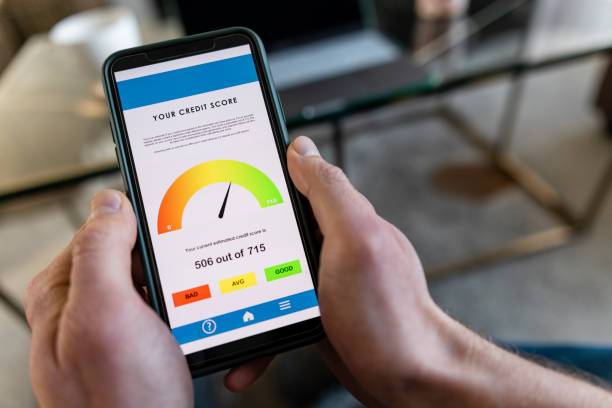
Your score can dip for a few common reasons. Maybe you used a bigger part of your credit card limit this month, or you paid a bill a little late. Sometimes, it’s because you applied for a new loan or credit card. Don’t panic! A small drop is normal and often temporary. Think of it like a warning light on your car’s dashboard. It’s not saying your car is broken, just that you should check what’s going on.
A credit card is a tool that lets you borrow money to buy things, with a promise to pay it back later. You need one to build a “credit history,“ which is like a report card for how you handle money. A good history helps you later for big goals, like renting an apartment or getting a car loan. Think of it as practice for bigger financial responsibilities. Using a card wisely shows banks you can be trusted.
No, this is a common myth! Having a zero balance reported is perfectly fine and does not hurt your score. Your positive payment history is still recorded every single month. What can help your score even more is if a small balance (like $10) gets reported to the credit bureaus before your due date, showing you’re using the card. You then pay that off in full by the due date to avoid interest. The key is to never carry a large, expensive balance from month to month.