6 months 3 weeks ago
Stores love to ask that one question at the register: “Want to save 20% today by opening a store card?” It sounds like free money. You sign a little pad, get a discount on your purchase, and walk out feeling smart. But that feeling usually fades fast when the first bill arrives. For most people in their twenties and thirties, store cards are one of the worst financial traps you can step into. Not because they’re illegal or sneaky, but because they’re designed to make the store money, not to help you build credit.First, let’s talk about what a store card actually is. Unlike a regular credit card that works anywhere Visa or Mastercard are accepted, a store card only works at that one brand or its sister stores. Some big retailers have cards that can be used anywhere, but those are less common. The limited use alone should be a red flag. Why would you open a line of credit that is useless outside one mall? The only reason is that initial discount. And that discount is basically bait.Here’s how the bait works. You save 20% on a $100 purchase, which means you save $20. Great. But the store card’s interest rate is often 25% to 30% or even higher. Regular credit cards hover around 20% on the high end, and you can find better ones. So you’re borrowing at a much worse rate just to get that one-time discount. If you pay off the full balance before the due date, you don’t owe interest. But most people don’t. In fact, stores know exactly how likely you are to carry a balance. That’s why they push the card so hard.The real killer is something called deferred interest. You might see a promotion that says “No interest if paid in full within 12 months.” That sounds great, but it’s not the same as a 0% intro APR. With deferred interest, if you fail to pay off the entire balance by the end of the 12 months, you get charged all the interest that would have accrued from day one. That means if you bought a $1,500 couch and paid off $1,499.99, you still get hit with interest calculated on the full $1,500 for the whole year. That interest could be $400 or more. Suddenly that couch costs almost $2,000. It’s not a scam, but it’s certainly a trap that catches thousands of young Americans every year.Even if you plan to pay off the balance on time, store cards can hurt your credit score in ways you don’t expect. One issue is the credit pull. When you open a store card, the store’s bank does a hard inquiry on your credit report. That can knock a few points off your score. That’s not a big deal by itself, but if you open several store cards in a year because each one offers a discount, those inquiries add up. More importantly, a new account lowers your average account age. For someone who just started building credit, this can be a real setback.Another problem is your credit utilization. That’s the percentage of your available credit that you’re using. Store cards often come with very low credit limits, like $300 or $500. If you put a $200 purchase on a $500 limit card, your utilization is 40%, which is too high. Credit scoring models look at total utilization across all your cards. Opening a store card with a tiny limit can push your overall utilization up, which makes you look riskier to lenders. That can raise the interest rates on your other cards or stop you from getting approved for an apartment rental.There’s also the temptation factor. Store cards are made to be used in the moment. You see a sale, you remember you have JCPenney card, and you buy something you didn’t plan on. This is how people end up with a closet full of clothes they never wear and a pile of debt with 28% interest. For the 18-to-35 crowd, impulse spending is already a battle. Adding a store card to the mix is like keeping a bag of chips on your desk when you’re trying to eat healthy.So is there ever a reason to get a store card? Maybe, if you shop at that store every single month, and you always pay your balances in full, and the discount is significant. Some store cards offer perks like free shipping or reward points that can be valuable. But for the average person, the risks far outweigh the benefits. You can build credit just as well with a normal credit card that has no annual fee and gives you cash back. And you can use that card anywhere, not just at one store.If a store card already got you, don’t panic. The best move is to pay off the balance as fast as possible, especially if you fell into the deferred interest trap. Then cut up the card or just leave it in a drawer. Keeping the account open can help your credit score over time because it adds to your available credit and account age. But never close a store card with a balance, and don’t get another one hoping to fix a problem. One bad store card is enough.At the end of the day, remember that the cashier isn’t your financial advisor. They get a bonus for every sign-up. That 20% discount is not a gift. It’s a loan with a timer on it. Treat store cards like the high-cost, low-reward products they are. Your future credit score will thank you.Applying for many cards in a short time makes you look risky to banks. Each application causes a “hard inquiry” on your credit report. Too many of these inquiries can lower your credit score. Banks think, “This person needs a lot of money fast!“ and get nervous. It’s better to be patient and apply only for cards you really need and can get.
The biggest mistake is making late payments. Payment history is the most important part of your score. Even one payment 30 days late can hurt your score for years. Set up automatic payments for at least the minimum amount due. Life gets busy, so let technology help you protect your score. Always know your due dates and make paying on time your top priority.
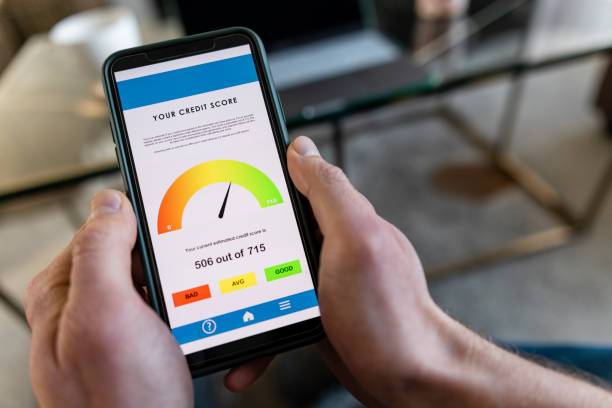
The easiest way is to use a free website or app. Many banks now show your score right in their own app. You can also use services like Credit Karma or Experian. They let you see your score anytime without paying a dime. Just remember, checking your own score this way never hurts it, so look as often as you like!
Typically, no. Companies like the electric, gas, or water company usually only report to the credit bureaus if you pay very late or not at all, which hurts your score. They don’t often report your good, on-time payments. To build credit, you need accounts that report all your payments. Focus on a credit-builder loan, a secured credit card, or a rent reporting service instead.
It’s the single biggest factor in your credit score! The score looks at how much of your credit limit you’re using, called your “credit utilization.“ Think of it like a test: using a small amount of your available credit (like under 30%) shows you’re responsible. Using most or all of your limit looks risky to lenders, even if you pay it off later. Keeping balances low proves you can manage credit wisely without relying on it too much.