4 months 1 weeks ago
Most people think building great credit means never missing a payment. That’s true, but it’s only half the story. The other half is what your balance looks like when your credit card company reports to the credit bureaus. That happens once a month, usually on your statement closing date. And here’s the thing most people never learn: that single snapshot is what determines your credit utilization, which is the second biggest factor in your credit score, right behind payment history. So you can pay your bill in full every month and still struggle to see your score climb, simply because you’re letting your balance get too high before that snapshot happens.The fix is a habit that takes about five minutes a month. Call it the two-statement trick. Instead of waiting for your monthly bill to arrive and then paying it all at once, you make two smaller payments. The first one lands a few days before your statement closing date. The second one is your regular payment after the statement comes out. That’s it. That little shift in timing can keep your reported balance low, which pushes your utilization down, which tells the credit scoring models that you’re a low-risk borrower. And over a decade, that makes a huge difference in the number you see when you check your score.Let’s make it concrete. Say your credit limit is $5,000. You typically charge about $1,500 in a month. If you just wait for the statement, your closing balance is $1,500. That’s 30% utilization, which is the threshold where lenders start to frown. But if you pay $1,200 a few days before the statement closes, your reported balance drops to $300. That’s 6% utilization. Scores love that. And you haven’t spent a single extra dollar. You’re just moving the same money around a few days earlier.The best part is that this habit builds on itself. Over months and years, your credit limit might go up because lenders see you using less of what you have. Your score creeps higher, which gets you better interest rates on car loans or mortgages. That saves real money. A two-point difference in a mortgage rate on a $250,000 home can mean tens of thousands of dollars in interest over the life of the loan. All because you took the time to make one extra payment each month.Now, you might be thinking about automation. That’s fine, but be careful. Most credit card companies let you schedule automatic payments, but the default is usually set to pay the minimum or the full statement amount on the due date. That doesn’t help with utilization. You need to set up a separate automatic payment that goes out a few days before your statement closes. Some banks let you schedule custom payments on specific dates. If yours does, set that up once and you’re done. If not, just put a recurring reminder on your phone for the 25th of every month, or whatever day works for your card’s closing date.Another thing to remember is that your closing date might not be the first of the month. It’s unique to your account. You can find it on your latest statement or by logging into your online account. Write it down. And if you have multiple cards, you’ll need to do this for each one. It’s a little bit of work at first, but after a month or two, it becomes routine. That’s what makes it a habit that lasts decades. It’s not a sprint. It’s just a small, consistent action that compounds over time.There’s also a psychological benefit. When you’re in the habit of checking your balance a few days before the statement closes, you become much more aware of your spending. You start to notice patterns. You see where your money goes. That awareness alone often leads to better decisions, like skipping that impulse buy or cutting back on a subscription you forgot about. So the habit improves your overall financial health, not just your credit score.And if you’re worried about the extra payment causing a cash flow problem, think about this: you’re paying the same total amount each month, just in two chunks. The first chunk might be $300, and the second chunk is the rest of the statement balance. As long as you have enough in your checking account to cover both, you’re fine. To avoid any confusion, you can even set the first payment to be a specific amount, like 50% of your typical monthly spending. Then the regular statement payment takes care of the remainder.One more tip: don’t obsess over getting your utilization to zero. A reported balance of $0 actually can be slightly worse than a tiny balance, because it looks like you’re not using your card at all. The sweet spot is anywhere from 1% to 10%. So don’t try to zero out your balance before the statement closes. Leave a small amount, like $50, on there. Then pay it off after the statement arrives. This shows lenders you’re actively using the credit line but keeping it under control.Start this habit today. Check your statement closing date, set up that first payment, and then watch your score do something it probably hasn’t done before: climb steadily, month after month, year after year. That’s the kind of quiet, boring habit that builds serious wealth over a lifetime. And the best time to start was five years ago. The second best time is right now.Focus on the one card you have or the one new card you get. Use it for small purchases and pay the full balance on time every single month. This builds a fantastic payment history, which is the biggest factor for a good credit score. Let your good habits with one or two cards build your score slowly and steadily.
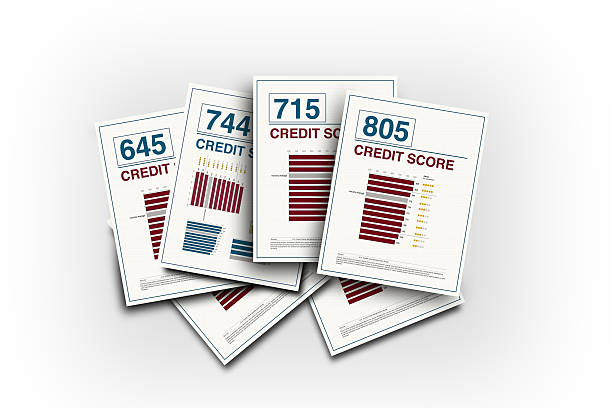
You don’t need a perfect score, but higher is always better. Many loans require a minimum score of 620, but that’s just to get in the door. To get the best rates and loan options, you should aim for a score of 740 or above. If your score is below 620, you’ll likely have a very hard time getting approved by most lenders. Don’t guess—check your score for free online well before you start house hunting so you know where you stand.
The easiest way is to set up automatic payments for at least the minimum amount due. You can also use a calendar on your phone with alerts a few days before each date. Another great trick is to pick one or two specific days each month to check all your accounts online. This way, you won’t be surprised by a due date you forgot about and you can avoid late fees.
The best first card is often a “starter” card made for people new to credit. Look for a “secured credit card,“ where you put down a small refundable deposit, or a “student card” if you’re in school. Avoid cards with yearly fees for your first one. Your own bank or credit union is a great place to start looking, as they already know you. The goal is just to get started building history.
Start with these three key alerts to build a strong safety net. First, turn on transaction alerts for any purchase over a small amount, like $1. This catches fraud immediately. Second, set up payment due date reminders so you never miss a bill and hurt your credit. Third, use low balance alerts to avoid overdraft fees. These basics give you peace of mind and help you manage your cash without any surprise problems.