1 month 4 weeks ago
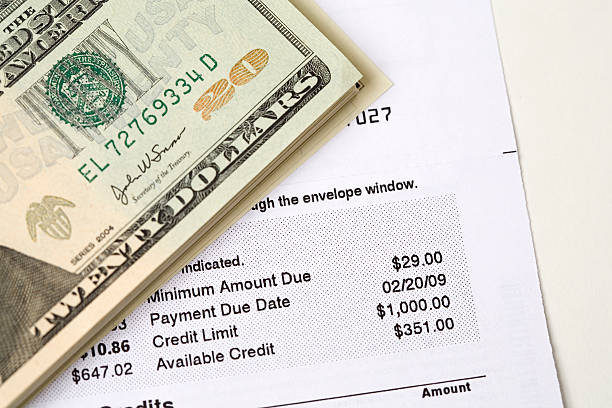
If you’ve ever looked at your credit card statement and seen a “payment due date” that’s a couple weeks after the “statement closing date,“ you might wonder what that gap is all about. That gap is called the grace period, and understanding it is one of the easiest ways to never pay a dime of interest on your everyday purchases.Here’s the basic idea. When you use a credit card, your purchases build up over a certain stretch of time called a billing cycle. At the end of that cycle, the card company sends you a statement that lists everything you bought. That day is your statement closing date. Then you get a payment due date, usually about three to four weeks after the closing date. The time between those two dates is the grace period.Why does that matter? Because if you pay off your entire statement balance by the due date, the card company won’t charge you any interest on those purchases. You basically got a free, short-term loan from the credit card company. Everything you bought during that billing cycle cost you exactly the sticker price, nothing extra. The grace period is your window to pay in full without interest.But here’s the catch. The grace period only works if you pay your balance in full every month. If you carry even a small amount of that statement balance into the next billing cycle, you’ll start getting hit with interest on the unpaid amount. Worse, on many cards, you’ll lose the grace period on new purchases too. That means the next time you buy a coffee or a pair of shoes, that purchase starts accruing interest from day one, even before your statement closes. This is how people get into debt spirals without realizing it.Let’s walk through a quick example so it feels real. Say your statement closes on the 10th of every month. Your payment due date is the 5th of the following month. You make a bunch of purchases between the 10th of May and the 10th of June. Your statement for those purchases arrives on June 10th, and your payment is due July 5th. As long as you pay the full amount shown on that June statement by July 5th, you pay zero interest on those May and June purchases. That’s a grace period of roughly 25 days.Now, what if you don’t pay the full amount? Say you only pay half. Then that unpaid half gets interest charged from the statement date, and your future purchases might start accruing interest immediately. That can make your debt grow faster than you expect. Interest rates on credit cards are usually high, often between 20% and 30% APR. If you let a balance ride, that free loan quickly turns into a pricey one.One thing to watch out for is the difference between your “current balance” and your “statement balance.“ Your statement balance is the exact amount you owed at the last closing date. Your current balance includes anything you’ve bought since then. If you want to avoid interest, you only need to pay the statement balance in full by the due date. You don’t have to pay the current balance if some of those purchases happened after the statement closed. But paying the statement balance in full automatically keeps you in the clear. If you pay less than that, you’re going to get interest charges.Another important thing about grace periods: they usually don’t apply to cash advances. If you use your credit card to get cash from an ATM, or to send a money transfer, those transactions almost always start charging interest immediately. There’s no 25-day window. You also often pay a separate fee. This is one of the most expensive ways to use a credit card, so you should generally avoid it unless it’s a true emergency.So how do you make the grace period work for you? The simplest trick is to set up automatic payments for at least the full statement balance each month. That way, you never miss a due date and you never accidentally carry a balance. Just make sure you have enough money in your checking account to cover it. If you can’t pay the full balance, at least make the minimum payment to avoid late fees and credit score damage. But remember, that means you’re paying interest.Also, know your due date. It’s usually the same day every month, but not always. Some cards let you pick a due date that works better with your pay schedule. If you get paid on the 1st and the 15th, you might ask your issuer to set your due date for the 3rd or the 18th. That can make it much easier to pay in full. Just call the number on your card and ask. It takes about two minutes.The bottom line is that the grace period is a gift. It lets you buy things now and pay for them later without any extra cost, as long as you respect the due date. Treat your statement like a bill that must be paid in full, and you’ll keep the power in your hands. Treat it like a suggestion, and you’ll be handing over money to the credit card company for nothing. Knowing the difference between your statement date and your due date is one of the smartest money habits you can build.Think of it as a savings plan that also builds your credit. You don’t get the money upfront. Instead, the credit union puts the loan amount (like $500 or $1,000) into a special locked savings account for you. You make small monthly payments for a set time, usually 6 to 24 months. When you finish all the payments, you get the money from the account, plus any interest it earned. The whole time, the credit union reports your good payments to the credit bureaus, which helps your score.
When you manage several cards well, you show banks you are very responsible. Paying every bill on time is the biggest help to your score. Also, if you keep the amount you owe low on each card, it improves your “credit utilization,“ which is a big part of your score. Think of each card as a chance to prove you’re a reliable borrower.
Paying down debt is one of the best things you can do for your score! A big part of your score is based on how much of your available credit you’re using (called credit utilization). As you pay off balances, this ratio gets better. Also, making every payment on time shows lenders you are responsible. Over time, your consistent payments will help rebuild your credit history, making you look much more trustworthy to future lenders.
Yes, it very likely could. Closing any card can hurt, but closing your oldest one is a double whammy. It shortens your credit history and also reduces your total available credit. This can increase your “credit utilization,“ which is how much of your limit you use. A higher utilization can lower your score. Even with other cards, that oldest account is a big part of your credit story.
Having a baby itself does not change your credit score. The credit bureaus don’t know about your new family member! What does affect your score are the financial choices you make because of the baby. If you miss payments on bills because you’re overwhelmed or take on too much credit card debt for baby items, your score will drop. The key is to stick to your budget and keep paying all your bills—like your credit card, car payment, and utilities—on time, every single month.