6 months 1 weeks ago
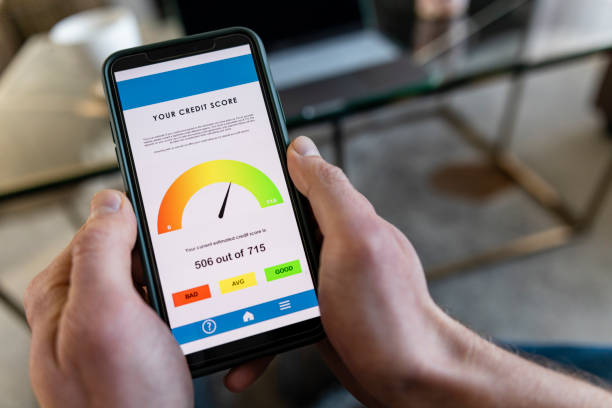
You have probably heard some version of this warning before: “Don’t check your credit score too often, it will lower your number.” Maybe a friend told you, or you saw it in a random online forum. It sounds almost logical, right? If checking your score counts as a “credit check,” then maybe lenders will think you are desperate for money. So you avoid looking. That is a huge mistake. The truth is simple and reassuring: checking your own credit score has zero effect on your score. You can look at it every day if you want. Nothing bad will happen.Why does this myth stick around? Because there are two different kinds of credit checks, and they are treated very differently. One kind is called a hard inquiry. That happens when a lender checks your credit because you are applying for a new loan, a credit card, or a rental lease. You give permission for that check. A hard inquiry can shave a few points off your score, and it stays on your report for about two years. That is where the fear comes from. But when you check your own score, you are not a lender. You are just a person looking at your own financial information. That is called a soft inquiry. Soft inquiries are completely invisible to lenders. They do not affect your score in any way, shape, or form. Soft inquiries also happen when a credit card company pre-approves you for an offer, or when an employer runs a background check. You are not applying for anything, so there is no reason to punish you.Here is the simplest way to think about it: Your credit score is a grades report for your money habits. Looking at your own report card does not change your grades. Only your actual behavior does. Paying bills late, using too much of your credit limit, or defaulting on a loan is what moves your score down. Opening your credit card app and seeing your current score is just observation. It is like stepping on a scale to check your weight. The scale does not make you heavier.So why should you check your score regularly? Because ignoring it is risky. Your credit score touches so many parts of your life. It can determine whether you get approved for an apartment, what interest rate you pay on a car loan, and even whether you can get a decent cell phone plan. If you never check, you might not find out about a mistake on your report until it is too late. For example, a bill from an old utility account might be reported as unpaid when you actually paid it. Or worse, someone might have opened a credit card in your name without your knowledge. That is identity theft, and the only way to catch it early is to look at your own credit on a regular basis.There are many free ways to keep an eye on your score. Most credit card companies now offer free scores to their customers through their apps or online accounts. Many bank apps do the same. You can also use well-known free services online that give you an updated score every month. These services make money by recommending financial products, not by charging you. And once a year, you are legally entitled to get a full credit report from each of the three major bureaus. That report shows every line of credit, every payment, and every inquiry. It does not include your score number, but it gives you the details that make up the score. The government website for that is annualcreditreport.com, and it is completely free. No strings attached.Some people worry that checking too often means they are obsessed or stressed about money. But in the 18 to 35 age range, you are building your financial foundation. Knowing your score helps you make better choices. If you see a dip, you can fix it quickly. If you see a steady climb, you know what is working. That kind of feedback is valuable. It is much better than staying ignorant and then getting rejected for a loan down the road.You also do not need to pay for a credit monitoring subscription unless you want extra alerts. The important thing is to build a habit of checking your score at least once a month. Put it on your calendar. Tie it to a routine, like the first day of the month. It takes less than five minutes. And every time you check, remind yourself that soft inquiries are your friend. They let you stay informed without any downside.The bottom line is easy to remember. You are the only person in the world who can look at your own credit without any penalty. Hard inquiries are for lenders. Soft inquiries are for you. Do not let an old myth stop you from taking control. Pull up your score today. Check it again next month. Check it again the month after that. Your score will not care. But your future self will thank you for being aware.Look for mistakes! Check that your name, address, and Social Security number are correct. Look at all your accounts and loans to make sure they are really yours. Make sure there are no late payments listed if you paid on time. Watch for accounts you don’t recognize, as this could be a sign of identity theft. If you see something wrong, you can dispute it to get it fixed.
A very safe rule is to wait at least six months between applications. Some experts even say to wait a full year. This gives your credit score time to recover from the last inquiry and shows banks you are not desperate. It also gives you time to learn how to use your new card responsibly before adding another one.
Think of your credit report as your school report card, but for money. It’s a detailed history of how you’ve handled loans and credit cards. Lenders look at it when you want to borrow money. It lists your accounts, if you pay on time, and how much you owe. It’s not your credit score—that number comes from the information in this report. Your job is to make sure everything on this “report card” is correct.
Don’t panic! Mistakes happen. You need to “dispute” the error, which just means telling the credit company it’s wrong. Write a letter to the credit bureau that shows the mistake. Clearly explain what’s wrong and include copies of any proof you have, like a bill showing you paid. They must investigate, usually within 30 days, and fix the error if you’re right. This can help improve your credit.
Think of your credit score like a grade for how you handle borrowed money. It’s a three-digit number that tells lenders, like banks or credit card companies, if you’re likely to pay them back. A good score makes life easier and cheaper! You’ll get approved for apartments, car loans, and credit cards more easily, and you’ll pay much less in interest. A poor score can make these things hard to get and very expensive. It’s a key that unlocks better financial opportunities.