1 month 4 weeks ago
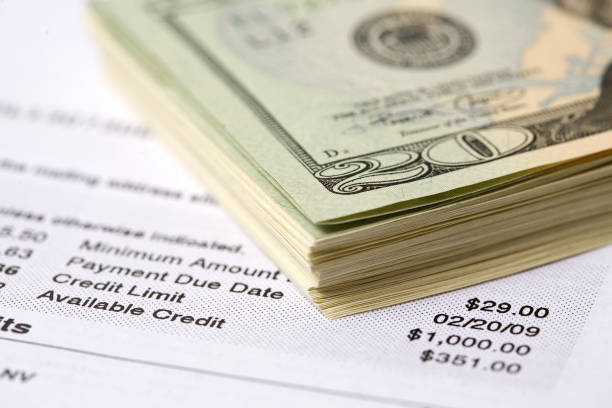
Most people think about credit scores only when they are applying for a loan or a new credit card. They check it, cross their fingers, and hope for the best. But in reality, your credit score is shaped by the small financial decisions you make every single day. The apps on your phone that you use to track your spending can have a huge impact on your credit score, even though they never directly show you your score. That is because budgeting apps help you stay in control of your money, and being in control of your money is exactly what leads to a healthy credit profile.The number one factor that affects your credit score is whether you pay your bills on time. Late payments can hurt your score for years, and they are often the result of simply forgetting or losing track of the date. Budgeting apps solve this problem by putting your payment deadlines right in front of you. When you log in to see your spending for the week, you also see that your credit card payment is due in three days. Many apps let you set reminders that ping your phone a few days before the due date. That might sound like a small thing, but it makes a massive difference. If you never miss a payment because your app reminds you, your score will gradually climb.Another way budgeting apps help your credit is by keeping your credit utilization low. Credit utilization is the fancy term for how much of your available credit you are using at any given time. If you have a credit card with a thousand dollar limit and you owe eight hundred dollars, your utilization is eighty percent. That is high, and lenders view it as a sign that you are overextended. On the other hand, using less than thirty percent of your limit is considered good. Budgeting apps show you exactly how much you have spent on each card, so you can see when you are getting close to that thirty percent line. You can then decide to pause using that card until your next payment posts. Without a budgeting app, it is easy to lose track and blow past a healthy utilization level without even realizing it.Budgeting apps also give you a complete picture of your debt. When you have multiple credit cards, student loans, or a car payment, it can be overwhelming to keep track of it all in your head. A good budgeting app shows all your debts in one place, with their balances and interest rates. Seeing everything together helps you plan how much extra money you can throw at a specific debt. Paying down high-interest credit cards not only saves you money on interest, it also lowers your utilization, which helps your credit score. The more you can reduce what you owe, the better your score becomes. Budgeting apps make this process feel less like a chore and more like a game, because you can watch your balances go down over time.There is also a simpler connection between budgeting and credit. When you track every dollar you spend, you naturally become more aware of your habits. You notice that you are spending sixty dollars a month on coffee or that you keep ordering takeout even though you have groceries at home. That awareness leads to better decisions. When you spend less than you earn, you do not need to lean on your credit cards to cover basic expenses. You might even pay your statement balance in full every month, which means you never pay interest and you never carry a high balance. That is the absolute best thing you can do for your credit score. People who use budgeting apps often find themselves in this position because the app forces them to face their spending reality.Finally, budgeting apps help you build a buffer. When you set a budget for the month and stick to it, you start to have money left over. You can put that extra money into a savings account. When an unexpected expense pops up, like a car repair or a medical bill, you can use your savings instead of pulling out a credit card. That means your credit utilization stays low even during emergencies. A budgeting app helps you create that safety net by showing you where your money is going and where you can cut back. Over time, that safety net protects your credit score from the random surprises that life throws at you.Every person wants a good credit score, but most people do not know where to start. The answer is not some complicated financial strategy. It is simply paying attention to your money. Budgeting apps give you an easy way to pay attention. They remind you when bills are due, they show you your credit utilization, they keep all your debts in one place, and they help you build good habits. None of that directly changes your credit report, but all of it changes your behavior. And your behavior is what ultimately determines your score. So if you want healthier credit, pick a budgeting app that works for you. Use it every day. Let it show you the truth about your spending. You might be surprised at how quickly your credit score responds to something so simple.You should check it about once a month. Checking your own score through your bank does NOT hurt it—that’s a myth! A monthly check lets you see if your good habits are paying off. It also helps you catch mistakes or fraud quickly. Think of it like a monthly health check-up for your finances. Just set a reminder on your phone to log in and take a quick look. It only takes a minute.
Even with careful planning, surprises happen—like a major car repair or a new roof. With a strong credit history, you have options. You could qualify for a low-interest personal loan or use a credit card with a low rate. Bad credit would force you into high-interest loans that eat away at your savings. Good credit gives you a safety net that’s affordable and keeps your financial plan on track.
The biggest mistake is becoming complacent and not checking your credit reports. You might think, “My credit is fine, I don’t need to look.“ But errors can creep in, or identity theft can happen. You should check your free reports at least once a year. This is like a regular health check-up for your finances. Catching a problem early is much easier to fix than dealing with it years later when you need to apply for a loan.
Paying more than the minimum is a superpower for your credit! It helps you pay off your debt much faster and saves you a ton of money on interest charges. This lowers your “credit utilization,“ which is a big factor in your credit score. Think of it as taking a shortcut out of debt instead of walking the long, expensive path.
A great rule is to try to use less than 30% of your total credit limit. For example, if your limit is $1,000, aim to keep your balance below $300 when your statement is created. This shows lenders you’re responsible and not relying too much on credit. Staying well below your max is one of the fastest ways to build a strong credit score.