1 month 2 weeks ago
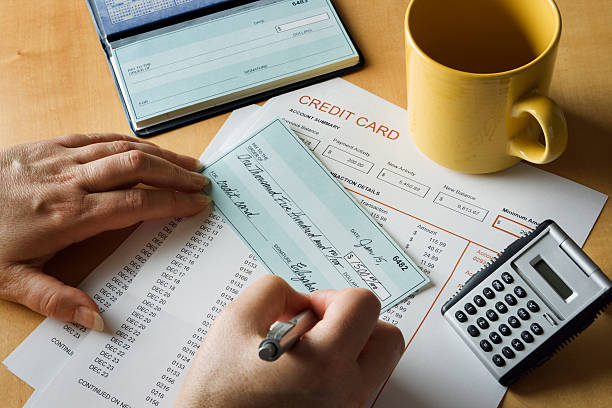
You open your credit card statement and see a charge you did not make, an amount that is too high, or the same payment posted twice. The fastest way to protect your money and your credit score is to act quickly, keep good records, and follow the dispute steps your card issuer requires.Start by reading the statement closely. Check every charge against your receipts, emails, and memory. Sometimes a strange name is just a store’s parent company, or a subscription you forgot to cancel. If you spot a real error, write down the date you found it, the amount, the merchant, and why you believe it is wrong. Take screenshots or save PDFs of receipts and order confirmations. This evidence will make your dispute easier to explain.If the charge came from a merchant you recognize, call or message them first. Many billing mistakes are simple mix-ups, and a refund from the merchant can be faster than a formal dispute. Ask for a confirmation email or reference number. If the merchant fixes the problem, check your next statement to make sure the credit appears. If the merchant will not help or you cannot reach them, move on to your card issuer.Your credit card company has a process for billing errors. Under federal law, you generally have 60 days from the date the bill with the error was sent to dispute it. Call customer service if you want, but also send a written dispute through the issuer’s secure message center, app, or mailing address. A phone call alone may not protect all your rights. Keep a copy of everything you send.In your dispute, include your name, account number, the date and amount of the charge, and a clear explanation of why it is wrong. Attach copies of receipts, emails, or other proof. Never send original documents. Ask the issuer to confirm in writing that they received your dispute. If you mail it, use certified mail with a return receipt. That may cost a few dollars, but it gives you proof of when the issuer got your letter.While the issuer investigates, you still need to pay the rest of your bill on time. This is the step people miss. If you withhold the entire payment because one charge is wrong, the issuer can report you late for the undisputed amount, and that can drop your credit score. Pay at least the undisputed portion and the minimum due. If you are not sure how much to pay, call the issuer and ask. They can tell you the amount that is not in dispute.The card issuer must look into your dispute. In most cases, they must acknowledge it within 30 days and resolve it within two billing cycles, or no more than 90 days. They cannot report the disputed amount as late while they investigate if you followed the rules. If they agree with you, they will remove the charge and any related fees or interest. If they disagree, they must explain why in writing. You then owe the amount, and you may want to file a complaint with the Consumer Financial Protection Bureau or your state attorney general.A billing dispute itself does not appear on your credit reports. What can hurt your credit is not paying your other bills on time or letting a real debt go unpaid. After the dispute is settled, check your credit reports for free to make sure the account is reported correctly. If a late payment or wrong balance shows up because of the dispute, file a separate dispute with each credit bureau. Include your card issuer’s letters and proof of payment.Finally, build habits that make billing errors less likely. Review your card activity every week instead of waiting for the statement. Turn on alerts for large charges and new merchants. Use virtual card numbers for subscriptions. Save receipts until the charge posts correctly. If you see a problem, deal with it right away. A calm, documented dispute is usually more effective than anger, and it protects the credit you are working hard to build.The rules are usually simpler than for a regular loan. You typically need to be a member of the credit union (which is easy to join), have a steady source of income, and be able to afford the monthly payments. They often don’t check your existing credit score heavily, because the whole point is to help you build it. The main thing they want to see is that you are reliable and can make those small payments each month.
You can get your three credit reports for free every week at AnnualCreditReport.com. That’s the only official, totally free site. For your score, check with your bank, credit card company, or a reputable free service. Never pay for this basic information. Setting a calendar reminder can help you remember to do your free checks.
Set up a simple system! The easiest way is to use automatic payments from your bank account for bills that stay the same, like your phone or car payment. For bills that change, like electricity, use calendar alerts on your phone. You can also make a list of all bills and their due dates at the start of each month so you have a plan.
Paying in full means you pay off the entire amount you spent that month. You then pay zero interest. The minimum payment is the smallest amount the bank will accept to keep your account in good standing. If you only pay the minimum, you’ll carry the rest of the balance over to the next month and start paying interest on it. This can make your purchases much more expensive in the long run.
The easiest way is often through a credit-builder loan. You don’t get the money upfront. Instead, you make small monthly payments into a savings account at a bank or credit union. After you finish all the payments, you get the money back, plus you’ve built a positive payment history! It’s a safe, simple tool designed just for people starting out. You prove you can make on-time payments, which is the biggest factor in your credit score.